A private conversation
Tell me what changed, whether you hope to stay or sell, and any deadlines you know about. We can begin in English or Spanish.
HOMEOWNER OPTIONS / SEATTLE & PUGET SOUND
You don’t need to know whether a short sale is the answer. Start with a private conversation about your home, your equity and the time you have to make a decision.
English & Spanish · No listing commitment for an initial conversation
FIRST, THE WHOLE PICTURE
Tell me what changed, whether you hope to stay or sell, and any deadlines you know about. We can begin in English or Spanish.
Compare likely market value with mortgage payoffs, other liens, selling costs and your moving needs. An estimate starts the discussion; it is not an appraisal or lender approval.
Consider a regular sale if there is enough equity, a short sale if necessary approvals are possible, or more information before deciding. If you want to stay, contact your servicer or a housing counselor about retention options.
PROPERTY. FINANCING. YOUR BOTTOM LINE.
My mortgage experience dates to 2005. I look at how payoff amounts, buyer financing, closing costs and contract terms affect what a sale can actually accomplish for you. The goal is to understand the numbers, negotiate thoughtfully and make the next step fit your situation.
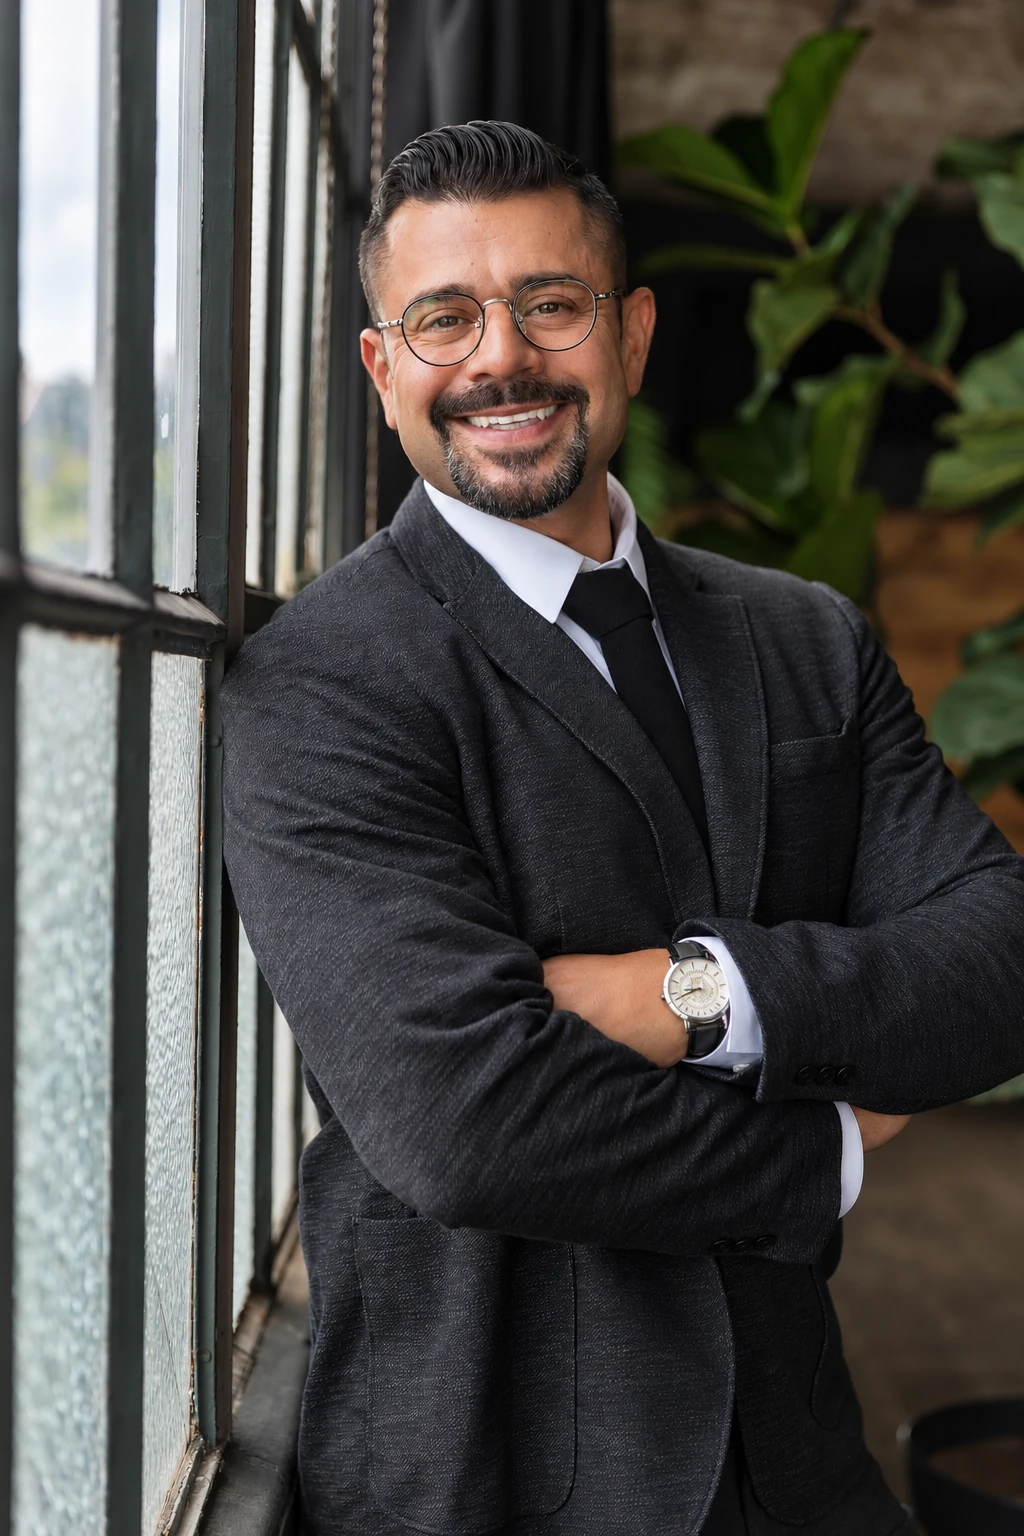
Enrique Pelayo Jr. — Owner & Designated Broker, The Broker Team
Washington real estate license #24653 · English & Spanish
Serving Seattle and homeowners in King and Snohomish counties.
Real estate representation is separate from legal advice, tax advice and housing counseling. Short-sale approval and foreclosure postponement are not guaranteed.
CLEAR ANSWERS TO DIFFICULT QUESTIONS
Being behind does not automatically prevent a sale. We need to review the property’s likely value, payoff amounts, liens and any foreclosure deadlines. A sale must be able to close under the applicable requirements. Contact your servicer about hardship options, and do not assume a listing or offer postpones an auction.
You may be able to sell through a regular sale rather than a short sale. Compare a realistic sale price with the full mortgage payoff, other liens, selling costs and moving expenses. Equity on paper is not the same as cash available after closing. We can organize that comparison before you decide.
A short sale may be an option if the necessary lender or servicer approvals can be obtained. It involves selling for less than the mortgage debt and requires more than accepting a buyer’s offer. Approval, timing and any remaining debt must be addressed in writing; a sale does not automatically cancel the unpaid balance. Review legal and tax consequences with qualified advisers.
An initial conversation does not require a listing commitment. If you choose representation, brokerage compensation and services are agreed in writing and compensation is negotiable. Closing costs, liens and any required seller contribution depend on your circumstances and, for a short sale, the approval terms. We will review the proposed costs and estimated net proceeds before you commit; we cannot promise a lender will cover everything.
Do not assume it does. Sending this form, listing your property, receiving an offer or requesting short-sale approval does not itself stop a foreclosure sale. Ask your servicer to confirm the status and any postponement in writing. If an auction is scheduled, contact a Washington housing counselor or attorney promptly instead of waiting for a website response.
CFPB: What is a short sale?
CFPB: Options to avoid foreclosure
Washington: Housing counseling, legal aid and mediation information
Reviewed September 23, 2026. Your loan terms, notices and circumstances determine the options available to you.